
Goldman has been pretty good on the Chinese property crash, being more bearish than most. But it’s not been bearish enough.
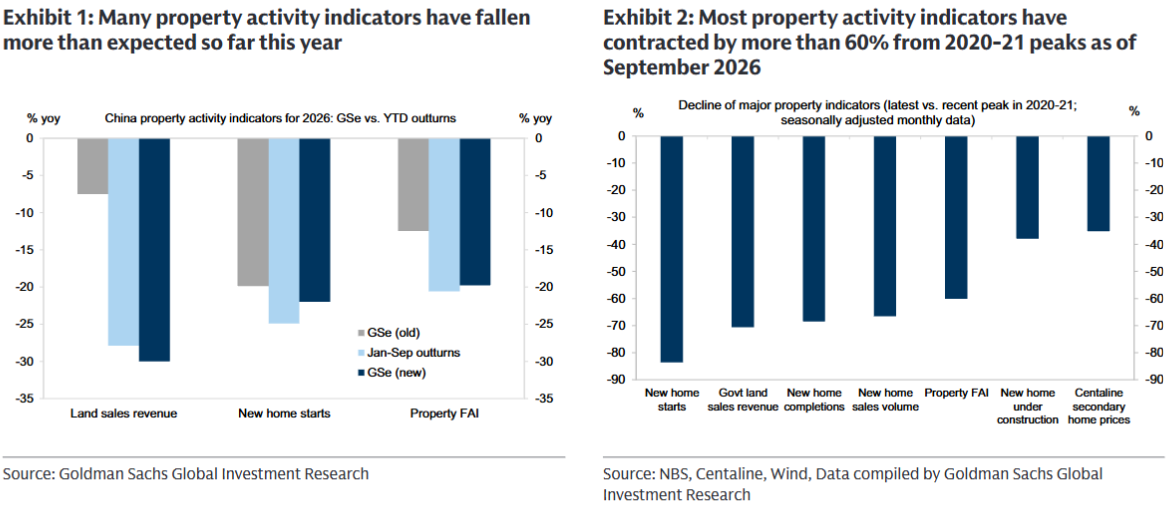
China’s property downturn is now in its sixth year. While we had projected then property sector’s drag to real GDP growth to narrow somewhat from last year to this year, most housing activity indicators have been much weaker than anticipated so far this year.
In addition, the recently announced shift from presales to completed-home sales implies tighter developer funding and lower property investment over the next few years.
Advertisement